 (888) 785-9923
Selling Your Business in Nevada: Legal Steps to Maximize Value and Reduce Risk

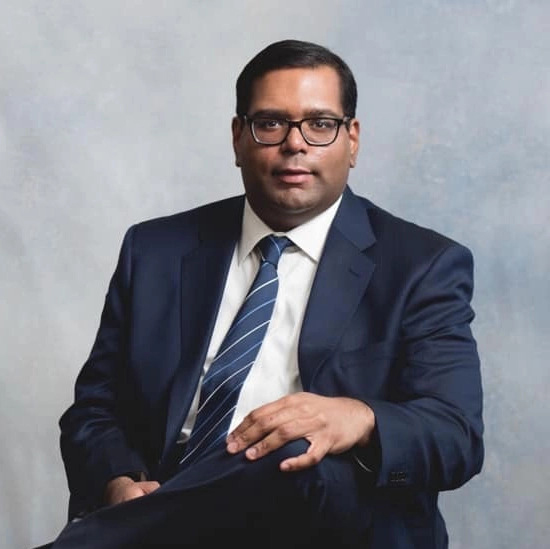
By Milan Chatterjee | Founding Attorney, Milan Legal
Selling a business in Nevada is a major legal and financial transaction, and the work required to protect the seller’s interests begins well before a buyer signs a purchase agreement. Owners need to understand what the business is worth, prepare for due diligence, choose the appropriate transaction structure, protect confidential information, and negotiate terms that limit unnecessary post-closing exposure. Working with a Mergers & Acquisitions Attorney (Nevada) early in the process can help a seller avoid problems that may reduce the purchase price or create disputes after closing.
A successful sale is not simply about finding a buyer willing to pay the highest headline price. The structure of the transaction, treatment of liabilities, payment terms, representations and warranties, indemnification obligations, escrow, earn-outs, taxes, and the seller’s continuing responsibilities can materially change the economic value of the deal. Careful preparation gives a seller more leverage to negotiate those terms before becoming committed to a transaction.
Prepare the Business Before Going to Market
The strongest time to identify legal problems is before a buyer finds them. Before marketing the business, the owner should review corporate or LLC records, ownership documents, major contracts, leases, licenses, permits, intellectual property, employee agreements, litigation, tax records, financing arrangements, insurance, and outstanding liabilities.
This preparation can also uncover inconsistencies that may become difficult during due diligence. For example, an important contract may not be properly assigned, an intellectual-property agreement may be missing, an old lien may still appear on a record, or an ownership document may not accurately reflect the current structure of the company. Resolving these issues before negotiations can make the business easier to diligence and reduce opportunities for the buyer to demand a last-minute price reduction.
Determine a Realistic Business Value
A seller should understand the business’s value before responding to offers. A valuation may consider revenue, normalized earnings, cash flow, tangible assets, intellectual property, customer relationships, goodwill, market conditions, comparable transactions, and future growth.
The valuation should also account for risks that a sophisticated buyer is likely to identify. Heavy customer concentration, dependence on the owner, declining margins, significant debt, unresolved litigation, unfavorable contracts, or outdated equipment can affect the price a buyer is willing to pay.
It is also important to distinguish between the business’s overall enterprise value and the amount the seller will ultimately receive. Debt, cash, working-capital adjustments, transaction expenses, escrow, earn-outs, seller financing, taxes, and other deal terms can significantly affect the seller’s net proceeds.
Prepare Your Business Before the Sale
Choose the Right Transaction Structure
One of the most important decisions is whether to sell the business through an asset purchase, stock purchase, membership-interest purchase, merger, or another structure. The choice affects what the buyer receives and which liabilities remain with the seller or the existing entity.
In an asset sale, the buyer generally identifies the assets and liabilities being acquired. This can provide flexibility but may require assignments, third-party consents, and separate treatment of different assets. In a stock or membership-interest sale, the buyer acquires ownership of the existing entity, which can provide continuity for contracts and operations but may require extensive diligence into the company’s historical obligations.
The structure can also affect taxes, licenses, employees, intellectual property, real estate, and closing requirements. Sellers should therefore evaluate the structure with legal and tax advisers rather than accepting the buyer’s preferred structure without understanding the consequences.
Organize the Due Diligence Materials
Once a serious buyer becomes involved, the seller will usually face a detailed due diligence process. Preparing a well-organized data room can make that process more efficient and demonstrate that the seller has a well-managed business.
Typical materials include financial statements, tax returns, organizational records, contracts, leases, licenses, permits, employee information, insurance policies, intellectual-property documentation, litigation records, debt documents, customer and supplier agreements, and information concerning material assets.
The seller should not simply upload every document without reviewing what is being disclosed. Confidential customer information, employee data, privileged legal communications, trade secrets, and other sensitive information may require appropriate handling. Legal counsel can help determine what should be disclosed, when it should be disclosed, and whether additional confidentiality protections are necessary.
Protect Confidential Information During Negotiations
A potential buyer may need access to sensitive information to determine whether the acquisition makes financial sense. However, the seller should not provide unrestricted access before establishing appropriate confidentiality protections.
A confidentiality agreement should address how information may be used, who may receive it, how sensitive information must be protected, and what happens if the transaction does not close. Depending on the transaction, the agreement may also address employee solicitation, customer information, trade secrets, and the return or destruction of confidential materials.
The seller should also consider how information is disclosed during different stages of diligence. Highly sensitive information may not need to be provided until the buyer has demonstrated sufficient seriousness or the transaction has progressed to a later stage.
Carefully Negotiate the Letter of Intent
A letter of intent often establishes the commercial framework before the definitive purchase agreement is drafted. Sellers should pay close attention to the proposed purchase price, transaction structure, payment terms, due diligence period, exclusivity, confidentiality, financing conditions, and anticipated closing date.
The seller should also understand which provisions are intended to be binding. Confidentiality, exclusivity, expenses, governing law, access to information, and similar provisions may be binding even when the proposed purchase itself remains subject to a definitive agreement.
An LOI can establish negotiating expectations that are difficult to reverse later. Sellers should therefore avoid treating it as a routine administrative document and should have its terms reviewed before signing.
Protect the Seller in the Purchase Agreement
The definitive purchase agreement is where the transaction’s legal and economic protections become concrete. Sellers should pay particular attention to representations and warranties, indemnification, liability caps, baskets, survival periods, escrow, purchase-price adjustments, closing conditions, and post-closing obligations.
Representations and warranties should accurately describe the business without unnecessarily expanding the seller’s exposure. A seller should avoid making absolute statements when the underlying facts are qualified or dependent on information that may change.
Indemnification deserves particular attention because it can affect the seller’s financial exposure after closing. The agreement should establish which claims are covered, how long claims can be made, whether a deductible or basket applies, whether liability is capped, and whether any portion of the purchase price will be held in escrow.
Address Due Diligence Issues Early
Manage Liabilities and Tax Obligations
A seller should identify outstanding tax obligations before closing rather than waiting for the buyer to discover them. Nevada Department of Taxation guidance specifically addresses the sale or closure of a business and explains that sellers remain responsible for required returns covering the period in which the business operated.
Nevada also has successor-liability rules that can affect the buyer when purchasing an existing business. The Department of Taxation advises purchasers to request a Certificate of Amount Due and explains that a buyer may have liability for certain taxes and fees owed by the seller if the required procedures are not followed. This makes tax clearance an important closing issue for both sides of the transaction.
The seller should work with counsel and tax advisers to determine which liabilities will be paid at closing, which will remain with the seller, and which should be addressed through purchase-price adjustments, escrow, indemnification, or other contractual mechanisms.

Address Employees, Contracts, and Intellectual Property
Employees and business relationships can be critical to the value of an acquisition. Sellers should identify key employees, employment agreements, compensation obligations, benefits, accrued amounts, confidentiality agreements, and any pending employment disputes before the buyer begins diligence.
Contracts should be reviewed for assignment restrictions, change-of-control provisions, termination rights, renewal dates, and required third-party consents. A major customer or supplier agreement that terminates when the business is sold can materially affect the transaction.
Intellectual property also needs to be documented carefully. Trademarks, copyrights, software, domain names, proprietary systems, trade secrets, websites, and marketing assets should be properly identified and owned by the appropriate entity. Missing assignments or unclear ownership can create negotiation problems and reduce buyer confidence.
Negotiate the Payment Structure, Not Just the Price
A seller should evaluate the entire consideration package rather than focusing exclusively on the stated purchase price. Cash at closing generally provides greater certainty than contingent consideration, while earn-outs and seller financing can potentially increase the overall amount received but introduce additional collection and performance risks.
If an earn-out is proposed, the agreement should clearly define the performance targets, accounting methodology, measurement period, operational control, reporting rights, and dispute procedures. A seller should not accept an earn-out based on vague concepts such as “future profitability” without understanding how the buyer’s post-closing decisions could affect the calculation.
Seller financing similarly requires careful documentation of repayment terms, interest, security, default rights, and remedies. The economic value of deferred consideration depends partly on the buyer’s ability and obligation to pay it.
Prepare for Closing and Post-Closing Obligations
Closing should confirm that all agreed conditions have been satisfied and that the required assets, ownership interests, releases, consents, and payment arrangements are properly documented. The seller should retain complete copies of the final transaction documents and evidence of releases or payments.
After closing, the seller may still have obligations under the purchase agreement. These can include transition services, consulting arrangements, earn-out calculations, indemnification claims, escrow releases, tax filings, or assistance with transferring contracts and accounts.
Nevada’s Department of Taxation provides procedures for closing certain business tax accounts and notes that closing a tax account does not automatically close every other state or local registration. Sellers should therefore identify all applicable accounts and registrations rather than assuming that one filing completes the entire process.
Frequently Asked Questions
A seller should review ownership records, contracts, licenses, permits, taxes, employees, intellectual property, litigation, debt, insurance, and other liabilities before marketing the business. The seller should also determine the likely transaction structure and prepare for buyer due diligence.
Early legal advice can help identify issues that could reduce the purchase price or delay closing. An attorney can also help prepare confidentiality documents, review the transaction structure, negotiate the letter of intent, organize diligence, and prepare or negotiate the definitive purchase agreement.
Neither structure is automatically better. The appropriate structure depends on the business, tax considerations, liabilities, contracts, licenses, buyer preferences, and the seller’s financial and legal objectives. The seller should evaluate the consequences before agreeing to the buyer’s proposed structure.
The seller remains responsible for required tax filings and liabilities associated with the period in which the business operated. Nevada Department of Taxation guidance also explains procedures for closing applicable tax accounts and addressing outstanding obligations.
A seller can reduce post-closing risk through accurate representations, carefully negotiated indemnification provisions, liability caps and baskets where appropriate, reasonable survival periods, escrow limitations, clear disclosure schedules, and well-defined post-closing obligations. The specific protections should be negotiated based on the transaction and the seller’s risk exposure.
About Milan Chatterjee
Milan Chatterjee is a Nevada and California licensed attorney and the founder of Best Business Lawyer, the dedicated business law practice of Milan Legal. He earned his legal education at UCLA School of Law and studied as a visiting student at NYU School of Law. Before establishing his legal practice, he served as Associate Compliance Counsel at Las Vegas Sands Corporation. His practice focuses on providing practical legal guidance to Nevada businesses and their owners, including business transactions, contracts, business formation, disputes, and mergers and acquisitions.
Get Legal Help Selling Your Nevada Business
Conclusion
Selling a business in Nevada is a transaction that requires careful planning long before the closing date. Preparing the business records, understanding its value, choosing an appropriate transaction structure, organizing due diligence, and protecting confidential information can make the sale process more efficient and improve the seller’s negotiating position.
The purchase price is only one part of the deal. Payment structure, indemnification, escrow, representations and warranties, liabilities, taxes, contracts, employee obligations, and post-closing responsibilities can all affect how much value the seller ultimately receives and how much risk remains after the transaction.
A well-prepared seller enters negotiations knowing what the business is worth, which issues need to be resolved, and which terms cannot be accepted without additional protection. That preparation can help turn a complicated business sale into a more controlled and predictable transaction.

Get Immediate Legal Help
Free, confidential. We respond within minutes.
Related Articles
Milan Chatterjee
UCLA Law Graduate. Former in-house counsel at Las Vegas Sands Corp. Nevada & California Bar. Founding President, South Asian Bar Assoc. of Las Vegas.