 (888) 785-9923
Buying a Business in Reno, NV? Legal Documents Every Buyer Should Review

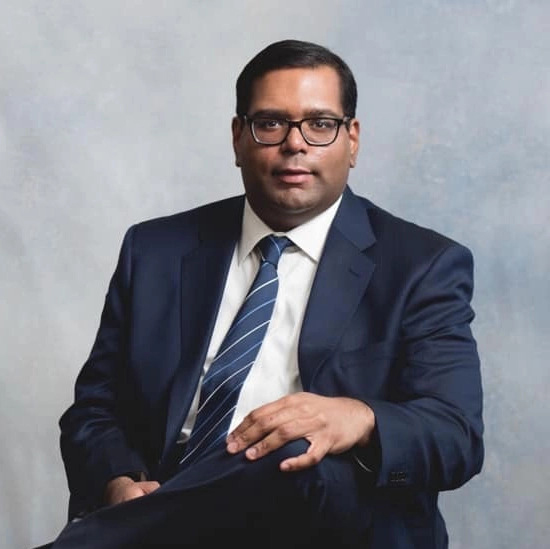
By Milan Chatterjee | Founding Attorney, Milan Legal
Buying an existing business can be one of the fastest ways to become an owner. Instead of building a customer base from nothing, you step into a company that already has revenue, staff, suppliers, a location, and a reputation. That head start is exactly what makes acquisitions so appealing, and it is also what makes them risky. When you buy a business, you are not just buying what you can see on the tour. You may also be inheriting contracts you have never read, debts that do not appear in the sales listing, employee issues that have not surfaced yet, and obligations that follow the business no matter who owns it. The documents you review before closing are your best tool for separating a solid opportunity from an expensive surprise, and having a business lawyer Reno NV buyers trust guide that review can protect both your investment and your personal finances.
The timing for buyers in Northern Nevada is especially interesting. Across the country, a large generation of business owners is approaching retirement, and many of them built companies without a clear succession plan. Industry observers have described this trend as a major transfer of small business ownership, and Reno is no exception. Established restaurants, contractors, service companies, retailers, manufacturers, and professional practices are coming to market as their founders step away. That creates real opportunity for buyers, but it also means many sellers have informal records, outdated agreements, and years of handshake arrangements that need careful examination before money changes hands. For an overview of legal services for Northern Nevada companies, visit our Reno and Lake Tahoe Business Lawyer page.
Know What You Are Buying Before You Sign
The documents behind a business tell the real story of its value and risks. Contact Best Business Lawyer to plan your due diligence and review key records before you commit to a purchase.
Start With the Letter of Intent and Confidentiality Agreement
Most acquisitions begin with a nondisclosure agreement and a letter of intent. The nondisclosure agreement allows the seller to share sensitive financial and operational information while protecting it from misuse. As a buyer, you should read it carefully, because some confidentiality agreements include restrictions on contacting employees, customers, or suppliers, or limit what you can do with the information if the deal does not close. Those terms can affect how thoroughly you are able to investigate the business.
The letter of intent outlines the proposed price, structure, payment terms, exclusivity period, and key conditions. Even when most of it is described as nonbinding, it sets the framework for everything that follows, and certain provisions such as exclusivity and confidentiality are often binding. This is the right moment to make sure the deal includes the protections you will need, such as a due diligence period, the ability to walk away if problems are discovered, a financing contingency if you are using a loan, and conditions tied to transferring the lease, licenses, and key contracts. Once these points are agreed, it becomes much harder to add them later.
Confirm the Structure: Asset Purchase or Ownership Purchase
Before diving into individual documents, it is important to understand how the deal is structured, because the structure determines what risks you inherit. In an asset purchase, the buyer acquires specific assets of the business, such as equipment, inventory, customer lists, intellectual property, and goodwill, and typically assumes only the liabilities it agrees to take on. In a purchase of the ownership interests, such as buying the membership interests of an LLC or the stock of a corporation, the buyer steps into the existing company along with its history, including liabilities that may not yet be known.
Many small business acquisitions are structured as asset purchases because they offer buyers more control over what they take on. However, asset purchases can make it harder to transfer certain contracts, licenses, and permits, and tax consequences differ for both sides. Ownership purchases may be necessary when the business holds licenses or contracts that cannot easily be assigned. Each structure calls for a slightly different focus in due diligence, and the choice should be made with input from both legal and tax professionals.
Review the Company’s Organizational and Good Standing Records
Whether you are buying assets or ownership interests, you need to confirm that the seller actually has the authority to sell what is being offered. Request the company’s formation documents, operating agreement or bylaws, ownership records, and any agreements among the owners. Check the company’s status with the Nevada Secretary of State to confirm it is in good standing and that annual filings and the state business license are current.
Ownership documents deserve close attention. If the business has more than one owner, all required approvals must be obtained for the sale. Prior agreements may give other owners rights of first refusal or consent rights that affect the transaction. If the business has issued equity to investors, employees, or family members over the years, those interests need to be identified and addressed. Discovering an undocumented co owner or an unresolved ownership claim after closing can create serious complications.
Examine Financial Statements and Tax Records
Financial records are at the heart of any business valuation. Buyers should request several years of profit and loss statements, balance sheets, tax returns, bank statements, accounts receivable and payable reports, and sales records. Comparing tax returns against internal financial statements and bank deposits can reveal discrepancies, including revenue that may be overstated in marketing materials or expenses that were not properly recorded.
Pay particular attention to add backs, which are adjustments sellers make to show what they believe the business would earn under new ownership. Some adjustments are legitimate, such as removing an owner’s personal expenses, but others can be aggressive. Your accountant can help evaluate these figures, while your attorney can make sure the seller’s financial representations are reflected in the purchase agreement so you have recourse if they turn out to be inaccurate.
Tax records also matter for another reason. In some situations, a buyer can become responsible for certain unpaid taxes of the seller, including sales and use tax obligations owed to the state. Confirming that the seller’s tax filings and payments are current, and structuring the transaction to address any unpaid amounts at closing, helps prevent you from paying the seller’s tax bill after the deal is done.
Search for Debts, Liens, and Encumbrances
A business may look profitable while carrying significant debt. Request copies of all loan agreements, lines of credit, equipment financing, leases of equipment, and promissory notes. Ask whether any owners have personally guaranteed business obligations, since those arrangements will need to be addressed at closing.
Lien searches are an essential step. UCC filings with the Nevada Secretary of State can reveal lenders or creditors who have claimed a security interest in the business’s equipment, inventory, receivables, or other assets. Judgment and tax lien searches can uncover additional claims. The purchase agreement should require that all liens be released at or before closing so that you receive the assets free of the seller’s debts. Without that protection, a lender could pursue the very equipment you paid for.
Protect Yourself From the Seller’s Liabilities
Review Material Contracts With Customers and Suppliers
The value of many businesses depends on a handful of key relationships. Ask for copies of all significant customer agreements, supplier and distribution contracts, franchise agreements, service contracts, and licensing arrangements. Review how long each contract lasts, what it requires, how it can be terminated, and whether pricing is fixed or subject to change.
One of the most important questions is whether each contract can be transferred to you. Many agreements require the other party’s consent before assignment, and some treat a change in ownership as a transfer requiring approval. If a major customer or supplier can terminate the relationship when the business is sold, the value you are paying for may disappear shortly after closing. Identifying these contracts early allows you to make consent from key parties a condition of closing or to adjust the price and structure accordingly. Customer concentration is another warning sign worth watching. A business that depends heavily on one or two customers carries more risk than its revenue alone suggests.
Do Not Overlook the Commercial Lease
For businesses that rely on a specific location, such as restaurants, retail shops, salons, clinics, and many service companies, the lease may be one of the most valuable assets in the deal. A great business in a location it cannot keep is a very different investment. Review the lease term, renewal options, rent increases, operating cost obligations, repair responsibilities, use restrictions, and personal guarantee requirements.
Most importantly, review the assignment clause. Many leases require landlord consent to transfer the lease to a buyer, and some allow the landlord to change terms, demand a new guarantee, or increase rent as a condition of approval. Speaking with the landlord early and making a satisfactory lease assignment or new lease a condition of closing helps protect you from purchasing a business only to lose its location. Working with a business lawyer Reno NV entrepreneurs rely on can help you negotiate the lease transfer and understand how its terms affect the long term value of the business.
Evaluate Employee Records and Workplace Practices
Employees are often one of the most valuable parts of a business, and they can also carry hidden liabilities. Request a list of employees with their roles, compensation, tenure, and classification as employees or independent contractors. Review employment agreements, offer letters, commission plans, bonus arrangements, the employee handbook, benefit plans, and any agreements with key staff.
Look carefully for compliance issues. Nevada has specific rules on wages, overtime, meal and rest breaks, and final pay, and misclassification of workers as independent contractors is a common problem in small businesses. Ask about any wage claims, discrimination complaints, workplace injuries, or government audits. Depending on the structure, some of these liabilities may follow the business after closing. You should also consider which employees are essential to keeping customers and operations running and whether retention or transition agreements are needed to keep them in place through the change of ownership.
Confirm Licenses, Permits, and Regulatory Approvals
Many businesses cannot legally operate without specific licenses and permits, and not all of them transfer automatically to a new owner. Request copies of the state business license, local licenses from the City of Reno, the City of Sparks, or Washoe County, health permits, contractor licenses, professional licenses, and any industry specific approvals. Confirm that each is current and in good standing.
Some industries require regulatory approval before a new owner can take control. Businesses involving alcohol, gaming, cannabis, healthcare, childcare, transportation, or contracting may require applications, background checks, or waiting periods before ownership can change. In some cases, buying the business without the proper approvals could put the license at risk or force operations to pause. Building these approvals into the timeline and making them a closing condition is essential.
Verify Intellectual Property and Digital Assets
A business name, logo, website, domain names, social media accounts, phone numbers, customer databases, software, recipes, and proprietary processes may all be part of what you are buying. Confirm that the business actually owns these assets and that they are included in the sale. Check whether trademarks are registered, who controls domain names and online accounts, and whether software is licensed in a way that can be transferred.
Ownership gaps are surprisingly common. A website may have been built by a freelancer who never assigned the rights. Social media accounts may be registered in an employee’s personal name. A logo may be similar to another company’s trademark. Customer data may be subject to privacy commitments that limit how it can be used. Identifying and resolving these issues before closing ensures you receive the full value of the brand and customer relationships you are paying for.
Investigate Litigation, Claims, and Insurance History
Ask the seller to disclose all current, pending, and threatened lawsuits, claims, government investigations, and regulatory notices, along with any disputes resolved in recent years. Court record searches can help confirm what the seller discloses. Even claims that seem minor may signal larger operational problems, such as recurring customer complaints or workplace issues.
Review the company’s insurance policies and claims history as well. Understanding what coverage the business has carried and what claims have been made can reveal risks and help you plan your own coverage after closing. In some cases, it may be appropriate to require the seller to maintain coverage for events that occurred before the sale.
Understand the Purchase Agreement Before You Sign
The purchase agreement is the most important document in the transaction because it determines what you are buying, what you are paying, and what protection you have if something goes wrong. Key sections include the description of assets or interests being purchased, excluded assets and liabilities, the purchase price and payment terms, adjustments for inventory or working capital, and conditions that must be met before closing.
Representations and warranties are the seller’s statements about the business, such as the accuracy of financial records, the absence of undisclosed liabilities, compliance with laws, and the condition of assets. Indemnification provisions determine whether and how you can recover losses if those statements prove false. Buyers often negotiate an escrow or holdback of part of the purchase price to secure the seller’s indemnification obligations. Disclosure schedules, which list exceptions to the seller’s representations, deserve careful reading because anything disclosed there may limit your ability to make a later claim.
The agreement should also address noncompetition and nonsolicitation commitments from the seller where enforceable, ensuring the seller cannot open a competing business down the street and take back the customers you just paid for. If the seller is financing part of the price, the promissory note and security agreement should be reviewed carefully, along with any personal guarantee you are asked to provide. Transition or consulting agreements can help ensure the seller remains available to introduce you to customers, suppliers, and staff during the handover.
Closing Documents and Post Closing Steps
At closing, a series of documents transfers the business to you. In an asset purchase, these often include a bill of sale, an assignment and assumption agreement for contracts, intellectual property assignments, the lease assignment or new lease, and lien releases. In an ownership purchase, documents typically include an assignment of membership interests or stock, updated company records, and resignations of former managers or officers. Payoff letters from lenders and tax clearance documentation help confirm that the seller’s obligations have been satisfied.
After closing, there is still work to do. You may need to update filings with the Nevada Secretary of State, obtain or transfer licenses and permits, register for taxes, set up payroll and insurance, notify customers and vendors, and update bank accounts and online platforms. Keeping a complete set of closing documents organized will be valuable if questions or claims arise later.
Red Flags Buyers Should Not Ignore
Certain warning signs deserve extra caution during due diligence. These include financial records that do not match tax returns, a seller who is reluctant to provide documents or allow reasonable investigation, heavy dependence on a single customer or the owner’s personal relationships, key contracts or leases that cannot be transferred, unresolved lawsuits or tax issues, unexplained cash transactions, and employees classified as contractors without a clear basis.
None of these issues automatically means a deal should be abandoned. Many can be addressed through price adjustments, special indemnities, escrow arrangements, or closing conditions. The important thing is to identify them before closing, when you still have leverage, rather than after the purchase price has been paid. A thorough review guided by a business lawyer Reno NV companies trust helps you make that decision with clear information.
Buy Your Reno Business With Confidence
About Milan Chatterjee
Milan Chatterjee is a Nevada and California licensed attorney and the founder of Best Business Lawyer, the dedicated business law practice of Milan Legal. He studied at UCLA School of Law and was a visiting student at NYU School of Law. Before founding his practice, he served as Associate Compliance Counsel at Las Vegas Sands Corporation. His practice focuses on providing practical legal guidance to Nevada businesses navigating transactions, contracts, disputes, and business growth.
Frequently Asked Questions
Key documents include organizational records, financial statements, tax returns, loan agreements and lien searches, customer and supplier contracts, the commercial lease, employee records, licenses and permits, intellectual property records, litigation history, insurance policies, and the purchase agreement.
Asset purchases often give buyers more control over which liabilities they assume, which is why they are common in small business sales. Ownership purchases may be necessary when contracts or licenses cannot easily be transferred. The right choice depends on the business, tax considerations, and the risks involved.
In some situations, yes. Buying ownership interests generally means inheriting the company’s existing liabilities, and even in an asset purchase, certain obligations such as some unpaid taxes or secured debts can create risk. Lien searches, tax clearance, and strong indemnification provisions help protect buyers.
Many leases require landlord consent before they can be assigned to a buyer. Landlords may request a new guarantee or changed terms. Buyers should review the lease early and make a satisfactory lease assignment or new lease a condition of closing.
The purchase agreement defines what you are buying, the price and payment terms, the seller’s representations about the business, and your remedies if those representations turn out to be false. Careful review and negotiation of this document is one of the most important steps in protecting your investment.
Conclusion
Buying an established business in Reno can offer a faster path to ownership, immediate revenue, and a foundation to grow from. But the true value of any business lies in the details found in its documents. Organizational records, financial statements, tax filings, debts and liens, customer and supplier contracts, the commercial lease, employee records, licenses, intellectual property, litigation history, and the purchase agreement itself all reveal what you are really acquiring and what risks come with it.
Taking the time to review these documents carefully, ask hard questions, and negotiate protections into the purchase agreement can prevent costly surprises after closing. With strong due diligence and a well structured transaction, buyers can step into ownership with confidence, knowing they understand both the opportunity and the obligations of the business they are taking over.

Get Immediate Legal Help
Free, confidential. We respond within minutes.
Related Articles
Milan Chatterjee
UCLA Law Graduate. Former in-house counsel at Las Vegas Sands Corp. Nevada & California Bar. Founding President, South Asian Bar Assoc. of Las Vegas.